The short answer
Yes, roofing work can raise the price of home insurance in some circumstances. It can also leave the price unchanged or reduce the risk an insurer sees. There is no automatic discount for fitting a new roof.
The outcome depends on the work, the roof type, the updated rebuilding cost and the insurer's own pricing. Ask your insurer before structural work starts and again when the work is complete.
Do not include an assumed insurance saving in the budget for a new roof. Replace or repair a roof because the building needs it, then ask the insurer to price the completed property correctly.
Why the price can rise during roofing work
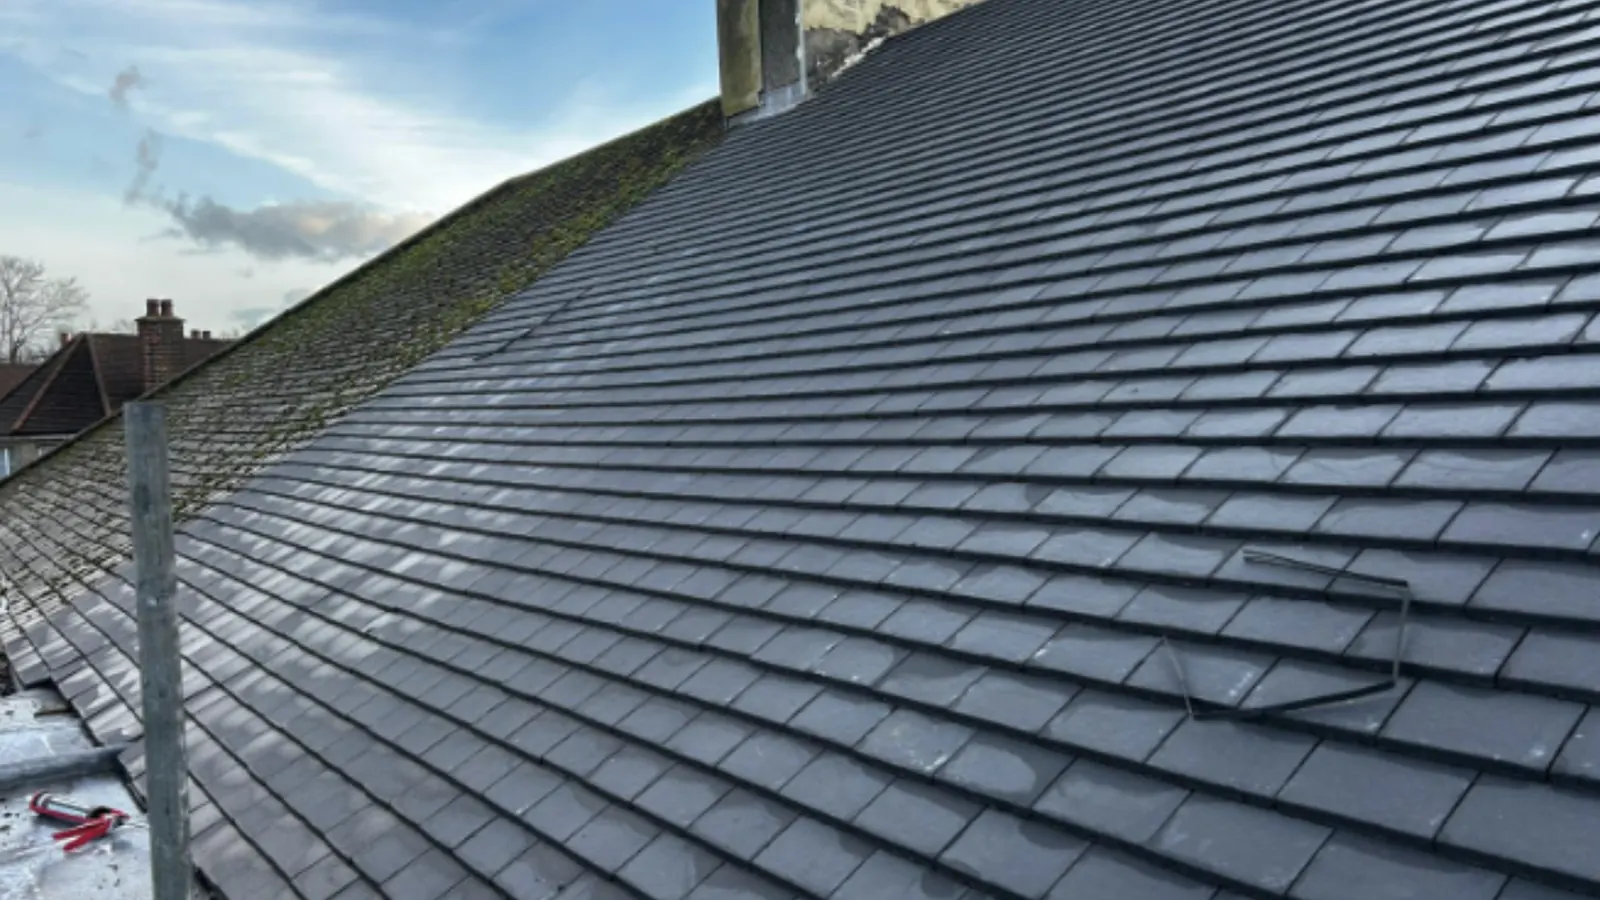
A major re-roof can temporarily expose the building to weather and bring workers, materials and access equipment onto the property. Standard home policies may limit damage arising from building work. Aviva's current guidance on home improvements says structural work can affect cover, the sum insured and the premium, and recommends contacting the insurer before work begins.
The finished work can also change the rebuilding cost. Insurance is based on the cost of rebuilding the property, not its sale price. If the specification or structure changes, the sum insured may need updating.
Roof type and condition can affect the price
Insurers do not assess every roof in the same way. Flat, thatched and other specialist roofs may have different conditions or pricing. Aviva's roof guidance says roof type can affect insurance cost and repair complexity, while the exact treatment depends on the insurer.
Maintenance matters too. The Association of British Insurers' home insurance guide explains that home insurance is not a maintenance contract and advises repairing known loose tiles or damaged guttering.
Can a completed new roof lower the premium?
Possibly, but it is not a rule. A sound roof may present less risk than an ageing or damaged one, but insurers price many other factors. The insurer may leave the premium unchanged, reduce it, or increase it because of wider rebuilding costs or changes to the property.
Keep the itemised quote, invoices, photographs, material warranties and completion documents. They give the insurer and any future surveyor a clear record of what changed.
What to tell your insurer
- What work is planned and whether any structural timbers will change
- The start date, expected duration and whether the home remains occupied
- The contractor's public liability cover
- Any change in roof covering, flat-roof proportion or other construction detail
- The final specification and updated rebuilding information after completion
Declaration requirements vary by policy. Check the policy documents and speak to the insurer rather than assuming that replacement tiles are cosmetic or that a full re-roof is automatically covered.
Repair or replace based on condition
Insurance should not decide whether a sound roof is replaced. Start with an inspection that distinguishes a local repair, a strip and recover, and structural replacement. Our guide explains how to tell whether a roof needs replacing, and our roofing service starts with an on-site survey and written scope.